Realtor or mortgage lender? Skip to the Flood Nerd Partner Toolkit →
Flood Nerd Blog · Cancellations & Refunds

Can I cancel my flood insurance and get a refund check? Yes — if your reason qualifies.

You can cancel an NFIP flood policy only for an approved reason, and the reason decides whether you get a full refund, a prorated refund, or nothing back. Here is the list, the steps, and the one question worth asking before you sign anything.

  • See if your reason qualifies for a refund
  • Know the documents you'll need
  • Avoid a lender force-placing a pricier policy
  • Find out if a better-priced policy is the real fix
Free comparison. No obligation. If keeping what you have is right, we'll say so.
Flood Nerd punching flood water
NFIP + PRIVATEboth compared
4.9/5 ★average rating
5,497+helped
465+client reviews
The quick answer

Yes, you can cancel flood insurance — but only for an approved reason.

FEMA lets you cancel an NFIP flood policy at any time, as long as your reason is on its approved list. Selling the home, paying off the mortgage, a map change that moves you out of the high-risk zone, or switching to a private flood policy are the most common. Your reason decides the refund: full, prorated, or none.

  • Lender still requires coverage? Canceling usually leads to force-placed insurance that costs more.
  • Canceling because of price? Shop it first. A better-priced policy is often the real fix.
  • Private flood policy? Your carrier's own terms apply, not the NFIP list.
Before you cancel

Is the problem the policy — or the price?

Most people looking up cancellation aren't selling a house. They opened a renewal bill, winced, and started wondering whether they need flood insurance at all. Before you cancel, take two minutes with the questions below.

Flood Nerd POV: Canceling saves money right up until the day water comes in. If cost is the reason, the smarter first move is to see what else is out there for your property. If nothing beats what you have, we'll tell you to keep it.
Never shopped it?

You may only have seen one price.

Many policies were set up at closing and never compared again. If your coverage came through a big-name insurer, it is often an NFIP policy with their logo on it. A comparison against the NFIP and private flood markets may turn up a different price or better coverage for the same home.

Think you won't flood?

Flooding doesn't follow the map lines.

FEMA reports that more than 20% of NFIP flood claims come from properties outside high-risk flood zones. Heavy rain, drainage backups, and snowmelt reach homes that have never flooded before — and standard homeowners insurance doesn't cover any of it.

Lender requires it?

Canceling can cost you more.

If your mortgage requires flood coverage and you cancel without a replacement, your lender can buy force-placed coverage and add it to your payment — usually at a higher price and with less protection. Canceling may also end any discount that depends on continuous coverage.

Valid cancellation reasons

The NFIP only allows cancellation for specific reasons.

Every NFIP cancellation is tied to an approved reason in FEMA's Flood Insurance Manual. These are the ones property owners use most. If yours isn't here, ask before you cancel.

  1. Property sale or removalYou sold the building, or it was demolished or moved.
  2. Contents sale or removalThe belongings insured under contents coverage were sold or moved out.
  3. Policy rewriteYour policy is being replaced with a new NFIP policy on the same building.
  4. Duplicate NFIP policiesTwo NFIP policies cover the same building. Keep one, cancel the other.
  5. Switching to a private flood policyYou bought replacement coverage from a private flood carrier. Timing affects the refund.
  6. Non-paymentThe premium wasn't paid. This ends coverage, with no refund.
  7. Ineligible riskThe building turns out not to be eligible for NFIP coverage.
  8. Closing didn't happenYou bought the policy for a purchase that fell through.
  9. Lender no longer requires itYour lender confirms in writing that flood coverage isn't required.
  10. Covered by the HOA's RCBAPThe condo association's master policy already covers the building.
  11. Mortgage paid offNo loan, no lender requirement — though the flood risk doesn't go anywhere.
  12. Canceled before the effective dateYou decided against the policy before coverage started.
  13. Payment errorA credit card or payment processing mistake.
  14. Map amendment (LOMA/LOMR)FEMA removes your building from the high-risk zone. How a LOMA works.
  15. Policy issued in errorThe policy was written for the wrong property or address.
Flood Nerd tip: Switching to a private policy is an approved reason in its own right. You don't have to wait for renewal to move — but line up the new policy before the old one ends so there is no gap.
How to cancel

How to cancel flood insurance, step by step.

  1. Confirm your reason qualifies

    Match your situation to an approved reason above. The reason sets both the paperwork and the refund, so get it right first.

  2. Line up replacement coverage if you need it

    If your lender requires flood insurance, or you just don't want a gap, have the new policy in place first. NFIP policies normally carry a 30-day waiting period, so a gap can't be fixed overnight.

  3. Gather your documents

    Depending on the reason: a closing statement or deed for a sale, a lender letter, a mortgage payoff letter, a LOMA or LOMR, or the declarations page of your new policy.

  4. Submit a signed cancellation request

    NFIP cancellations are made on FEMA's Cancellation/Nullification Request form, signed and submitted through your agent or insurer with your documents attached. We'll fill it out with you if we're your agent.

  5. Watch for confirmation and your refund

    Any refund is issued after the insurer processes the cancellation. Keep a copy of everything until the confirmation — and the check, if one is due — arrives.

Refunds

Will you get money back?

NFIP refunds fall into three buckets. Which one you land in depends on your cancellation reason and when the request is received.

Refund typeWhat it means
Full refundThe policy is treated as if it never took effect — for example, it was canceled before the effective date or written in error.
Prorated refundYou get back the unused part of the term. This is typical for mid-term cancellations like a sale or paid-off mortgage.
No refundSome reasons, like non-payment, end coverage without returning any premium.
Have a private flood policy? Private carriers set their own cancellation rules. Some refund the unused premium; others keep a minimum earned premium or charge a fee. Check your policy before you assume the NFIP rules apply.
What clients say

Homeowners, buyers, and lenders trust the Nerds.

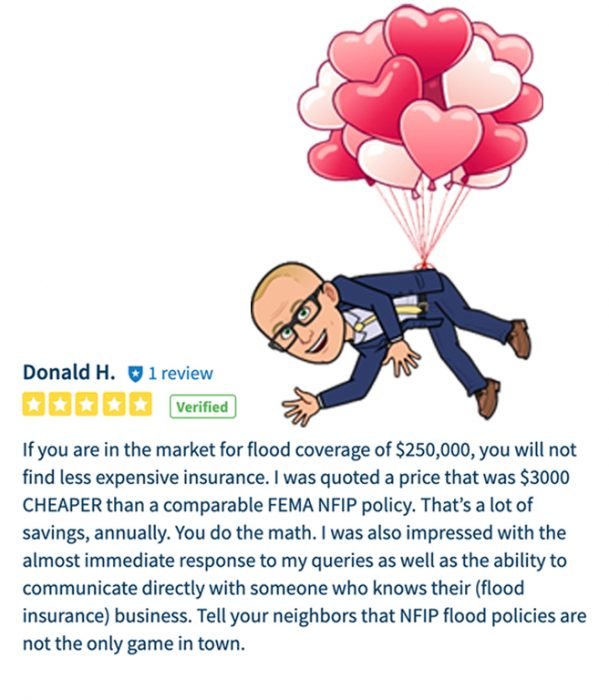
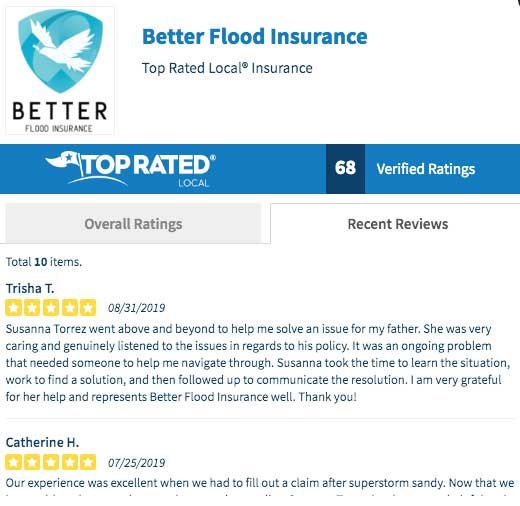
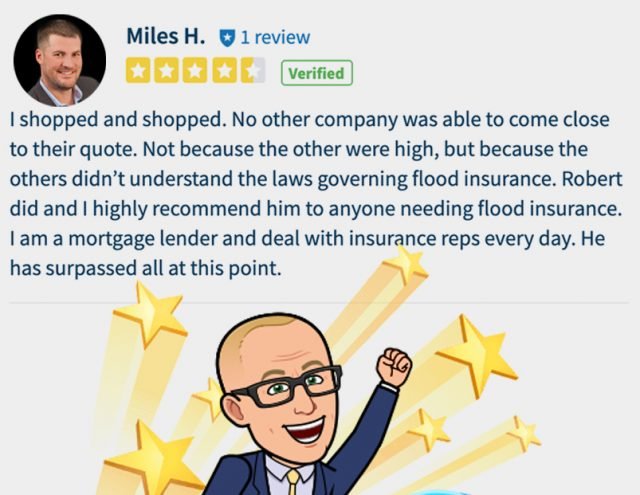
Flood Nerd review from a homeowner Client testimonial for the Flood Nerds Loan closing flood insurance review Better Flood Insurance review

Read more Flood Nerd reviews →

Better Flood featured on Top Rated Local, The New York Times, Money, Investopedia, Bob Vila, Newsy, and RealEstateRama
Thinking about canceling?

Have a Flood Nerd shop your policy first

If price is why you're here, find out what else your property qualifies for before you drop coverage. Here's what a Flood Nerd does — free.

The Flood Nerd Review
One clear recommendation: keep it, switch it, or cancel it.
  • ✓The multi-carrier shop$250 value

    We compare the NFIP and the private carriers that will actually write your property — so your decision comes from a real comparison, not a menu of one.

  • ✓The coverage recommendation$200 value

    We estimate your real rebuild cost and tell you what we’d buy — including replacement cost where the market offers it for your property. If you’d rather carry less, that’s your call, and you’ll make it knowingly.

  • ✓The fine-print flag$200 value

    We read the policy jacket before we recommend it, flag the terms that drive most flood claims — waiting periods, contents valuation, caps, major exclusions — and show you where the rest lives.

  • ✓A-rated carriers only$150 value

    We place coverage only with underwriters rated A- or better for financial strength.

  • ✓Lender-ready documentation$150 value

    We prepare the policy file to your lender’s standards, so flood isn’t the thing that slows your closing.

  • ✓One clear recommendation, ~24 hrsreal human

    From a licensed Flood Nerd — and every recommendation passes a second Nerd’s review before it reaches you.

What this review is worthReal work, done by a licensed Flood Nerd
~$950
$0 to find out
Why it costs nothing to find out: the shop, the comparison, and the recommendation are free, and you’re never obligated. We only earn anything if you decide we’ve found you something worth moving on.

Our promise: if the policy you already have is the right fit, we’ll tell you to keep it. We sell both the NFIP and private — so we have no reason not to.

Cancellation FAQ

Flood insurance cancellation FAQs

Can you cancel flood insurance and get a refund?

▾

Yes. FEMA allows you to cancel an NFIP flood policy for a set list of approved reasons, and several of them — like selling the property, paying off your mortgage, or a flood map amendment moving you to a lower-risk zone — can qualify for a partial or full premium refund.

How do I cancel my flood insurance?

▾

Contact your agent with your cancellation reason and supporting documents, submit a signed cancellation request, and wait for the carrier's confirmation. The paperwork required depends on which approved NFIP cancellation reason applies to your situation.

What are valid NFIP cancellation reasons?

▾

The most common are selling the property, paying off the mortgage, holding a duplicate policy, a lender letter stating flood coverage is no longer required, or a FEMA map amendment that places your property in a lower-risk zone. The full list is above.

Do you get money back if you cancel flood insurance early?

▾

Sometimes. Mid-term cancellations for approved reasons are typically refunded on a prorated basis, but reasons like non-payment do not produce a refund, and the money arrives only after the carrier processes and confirms the cancellation.

How do I get out of flood insurance my lender requires?

▾

You need either a lender letter stating coverage is no longer required or a FEMA map amendment (LOMA) showing your building sits outside the high-risk zone. Until one of those exists, canceling a lender-required policy usually triggers force-placed coverage that costs more.

Can I cancel my NFIP policy to switch to private flood insurance?

▾

Yes. Buying replacement coverage from a private flood carrier is an approved reason to cancel an NFIP policy, and it doesn't have to wait for your renewal date. Put the private policy in place first, then cancel, so your coverage never lapses. If you hold a discounted rate tied to continuous NFIP coverage, compare carefully before you switch.

Can I cancel a private flood insurance policy?

▾

Usually, but the NFIP's reason list doesn't apply. Each private carrier sets its own cancellation and refund terms — some return the unused premium, others keep a minimum earned premium or charge a fee. Read your policy, or send it to us and we'll tell you what it says.

Real estate agents & mortgage lenders

Deal fell through? Buyer's lender changed its mind? We handle the flood side.

We built a whole toolkit for the people who send us buyers — same-day quotes, a lender-ready file, closing scripts, and a direct line to a Nerd. When a closing collapses or a requirement changes, we sort out the cancellation paperwork so your client isn't stuck paying for coverage they no longer need.

Speak to a Flood Nerd™

Before you sign that cancellation letter, give us a call.

If you need to cancel, we'll walk you through it. If price is the real reason, we'll shop the NFIP and private flood markets for your property and tell you straight whether keeping, switching, or canceling makes the most sense.

Privacy & communication consent. Your information is never sold, and is used only to shop for flood insurance on your behalf. We're paperless — by submitting, you consent to texts and emails from Better Flood and Your Flood Nerds about your quote, policy, and relevant flood updates. You can opt out at any time. See our terms of use and privacy policy.

Estimates are drawn from real Better Flood quote data and are not a quote for your property. Coverage descriptions are general; the terms and exclusions of the issued policy control. Recommendations are based on the information you provide and the markets available for your property, and no statement on this page guarantees coverage will be offered or that any claim will be paid.
Scroll to Top