Should I Get a LOMA?
A real question from a client, and the honest answer we gave her about what a Letter of Map Amendment actually does — and does not do — before you cancel your flood coverage.
Can’t get a LOMA, or still waiting on one? See what flood coverage would actually cost you →
Should I Get a LOMA?
Amy
Hi Robert, thanks for the quote for flood insurance the cost isn’t as bad as I thought it would be. We are working with a surveyor to get our home mapped out of the Floodplain and are intending to cancel our insurance as soon as we get a LOMA. What will we need to go to cancel the policy once it is no longer needed?
What a LOMA Actually Does
Robert, The Flood Nerd
Let’s talk about what a LOMA really does. In the bureaucratic realm, sure, it exempts your property from a mapped flood zone. But does it change the topography of your land? Does it redirect water flow or build a barrier against torrential rains intensified by our changing climate? No, Amy. A LOMA doesn’t alter the earth’s behavior or shift the tide of meteorological events.
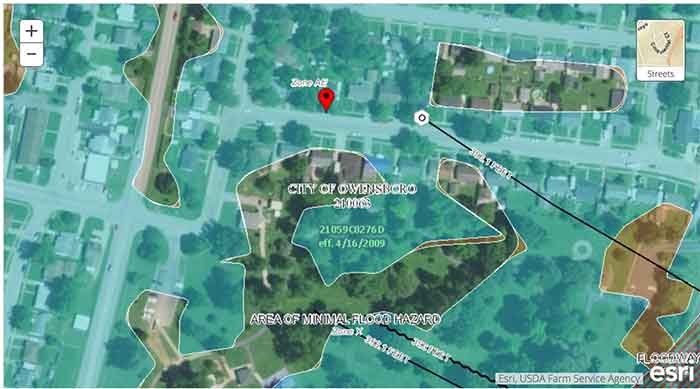
Take a look at your local map. See all that blue? Those are waterways, areas where—LOMA or no LOMA—water could potentially invade. Let’s not forget, water doesn’t adhere to the boundaries we draw; it obeys only the laws of physics.
Consider the economics of your decision. Flood damage doesn’t come cheap. Repairs could run you anywhere from $60,000 to an eye-watering $200,000. Think about it: Are you prepared to pull from your nest egg or burden yourself with high-interest loans? All the while, a flood insurance premium could have offered you the coverage you needed for a fraction of those costs.
Flooding has been and still is the is the #1 natural disaster the United State faces, costing billions in damage and ruined property as well as lost lives and displaced families.
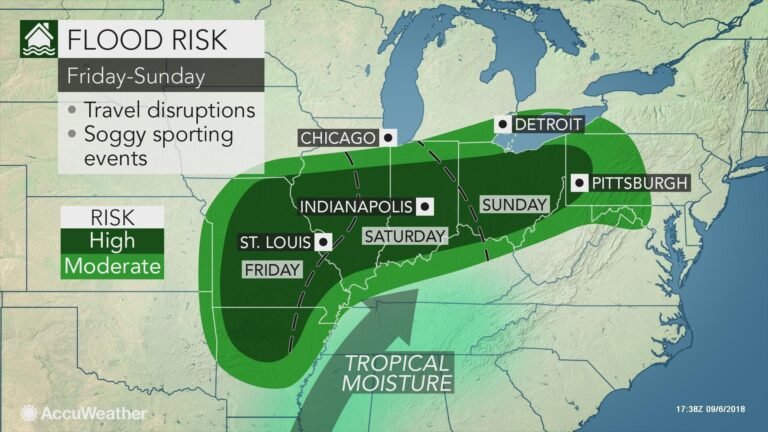
Let’s cut to the chase. Home insurance companies are not in the business of losing money. They exclude flood risks for a reason: they’re more likely to occur than, say, your home catching fire. You might be inclined to question this logic, but the statistics don’t lie. Flooding remains the United States’ #1 natural disaster, causing billions in damage and leaving countless lives in shambles.
You mentioned your mortgage lender will insist on flood insurance. That’s not a coincidence or a bureaucratic hiccup. It’s mandated by federal law for properties in high-risk flood zones, usually identified with an ‘A’ or ‘V’. You may think a LOMA would free you from this obligation, but many lenders still won’t let you drop the coverage. Why? Because the inherent flood risk remains. Your property’s proximity to a mapped floodway—essentially a fast-moving highway for floodwaters—should be a wake-up call.
Flooding is not covered on your homeowner’s policy.
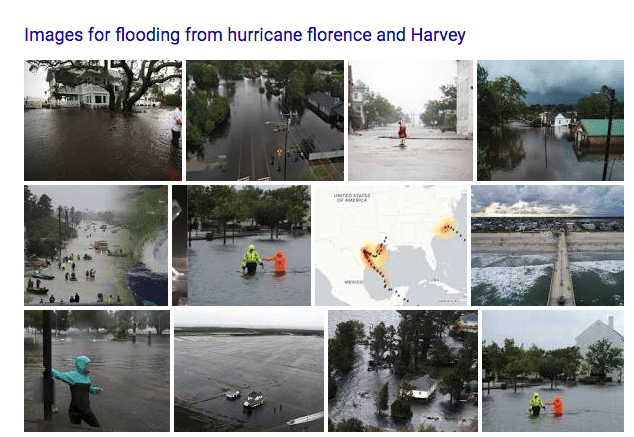
Let me share a stark reality. In recent floods in the Carolinas and Houston, a staggering 90% of those affected did not have flood coverage. Many of these homeowners resided in areas deemed low-risk—some of which were even rezoned due to political pressure. You see, Mother Nature doesn’t care about our laws or maps. She does what she wants, when she wants.
So, Amy, I’ll leave you with this. Insurance exists for a reason: to protect us from risks we hope never to face. It’s not a game of chance but a safeguard against the inevitable uncertainties of life. If your sole intention is to obtain a LOMA and drop your coverage, we might not be the agency you’re looking for. But if you’re open to truly protecting your property and your peace of mind, let’s talk.
Warm regards, Robert, Your Flood Insurance Advocate
LOMA’s do NOT remove the Risk of Flooding.
P.S. We have some phenomenal Preferred Risk Policies that could provide you with excellent coverage and affordable premiums. It’s something to think about, especially if that LOMA is still a few months out.
This is the type of honest conversation we strive to have with every client, focused on protecting not just property, but lives and peace of mind. If you’re navigating the complexities of LOMA and flood insurance, we’re here to offer real solutions for real risks.
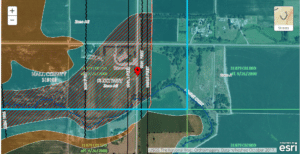
Mother nature doesn’t stay within our map lines.
I want you to please consider and note that 90% of those that flooded in both Carolina’s and Houston did not have flood coverage (NONE) this was because they were in what is considered a low-risk area, some of these areas have been mapped out due to political pressures (developers not wanting to sell NEW homes that will require flood insurance) some of these areas have never seen the flood waters before. I am willing that ALL of these 600,000+ properties believed it wouldn’t happen to them.
Insurance is there to cover your risk, Home insurance, auto insurance, life insurance and we really hope to never use it. I hope you never ever ever have a flood; I also hope that if you do at least you have some kind of coverage.
If you are looking to just get a LOMA and drop your Coverage, then I don’t know if the FLOOD NeRD is the best to write your policy.
MY thoughts. Welcome yours.
YOUR FLOOd NeRD
Have a Flood Nerd review your LOMA decision
A LOMA can be the right call, or it can leave you exposed. Here’s what a Flood Nerd does before you drop coverage — free.
-
✓The multi-carrier shop$250 value
We compare the NFIP and the private carriers that will actually write your property — so your decision comes from a real comparison, not a menu of one.
-
✓The coverage recommendation$200 value
We estimate your real rebuild cost and tell you what we’d buy — including replacement cost where the market offers it for your property. If you’d rather carry less, that’s your call, and you’ll make it knowingly.
-
✓The fine-print flag$200 value
We read the policy jacket before we recommend it, flag the terms that drive most flood claims — waiting periods, contents valuation, caps, major exclusions — and show you where the rest lives.
-
✓A-rated carriers only$150 value
We place coverage only with underwriters rated A- or better for financial strength.
-
✓Lender-ready documentation$150 value
We prepare the policy file to your lender’s standards, so flood isn’t the thing that slows your closing — whether or not the LOMA has come through yet.
-
✓One clear recommendation, ~24 hrsreal human
From a licensed Flood Nerd — and every recommendation passes a second Nerd’s review before it reaches you.
Our promise: if dropping coverage after your LOMA really is the right move for your property, we’ll tell you that too. We sell both the NFIP and private — so we have no reason not to.
Coverage descriptions are general; the terms and exclusions of the issued policy control. Recommendations are based on the information you provide and the markets available for your property, and no statement here guarantees coverage will be offered or that any claim will be paid.
Can’t get a LOMA? Let’s at least see what the cost would be.
Whether your LOMA is already in hand or still a few months out, we'll give you a straight answer on whether it's safe to cancel — and show you what flood coverage would actually cost either way, no pressure.
Privacy & communication consent. Your information is never sold, and is used only to shop for flood insurance on your behalf. We're paperless — by submitting, you consent to texts and emails from Better Flood and Your Flood Nerds about your quote, policy, and relevant flood updates. You can opt out at any time. See our terms of use and privacy policy.
Estimates are drawn from real Better Flood quote data and are not a quote for your property. Coverage descriptions are general; the terms and exclusions of the issued policy control. Recommendations are based on the information you provide and the markets available for your property, and no statement on this page guarantees coverage will be offered or that any claim will be paid.